
FT Partners Quarterly FinTech Insights and Annual Almanac
FT Partners is the only data source for comprehensive, global FinTech deal activity covering M&A, Financing and IPO statistics and trends
FT Partners’ FinTech Insights Reports are published on a quarterly basis, along with a comprehensive year-end Almanac. All information included in the reports is sourced from FT Partners’ Proprietary Transaction Database, which is compiled by the FT Partners Strategic Insights Team through primary research and data analysis. The reports feature M&A, financing and IPO statistics and trends as well as breakdowns by FinTech vertical, geography, investor-type and much more.
Also view our quarterly InsurTech Insights reports here.
Be sure to check back for quarterly updates and additions. All recent reports can be viewed or downloaded for free below.
Q3 2026 FinTech Insights
Report features:
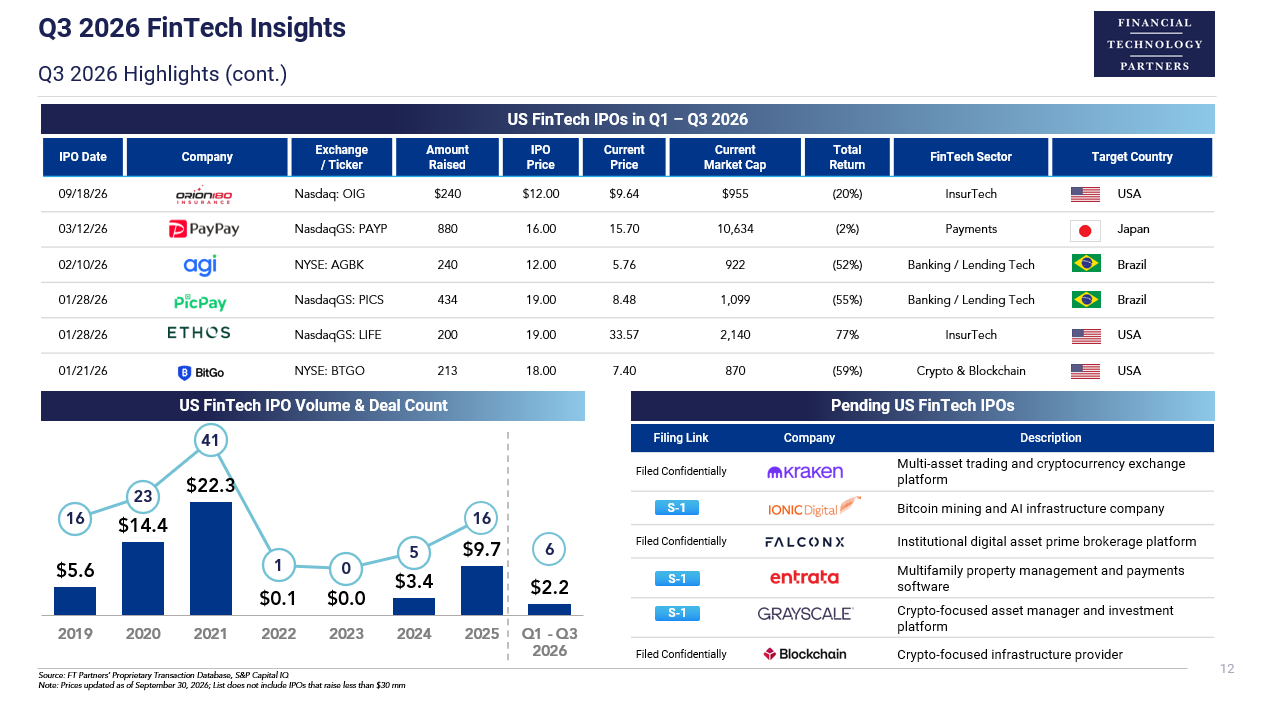
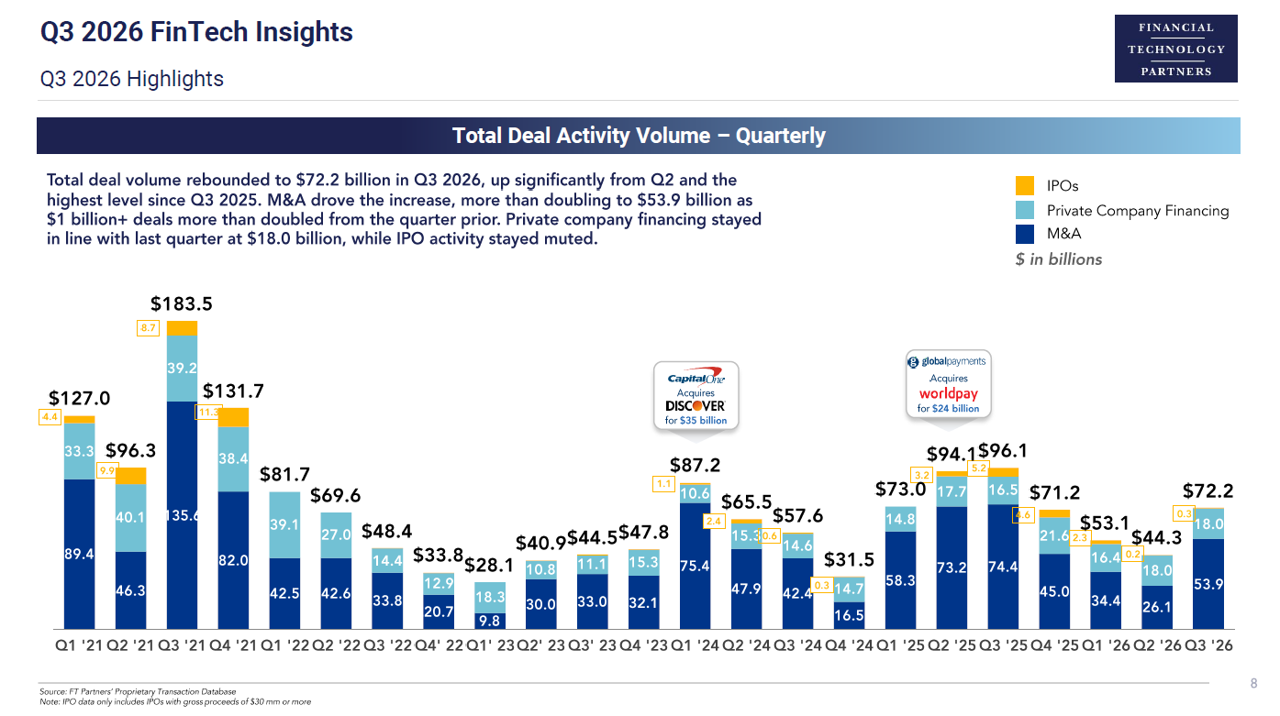
Q3 2026 and historical FinTech financing, IPO and M&A volume and deal count statistics
Largest FinTech financings and M&A transactions in Q3 2026
Most active FinTech investors including strategic investor participation
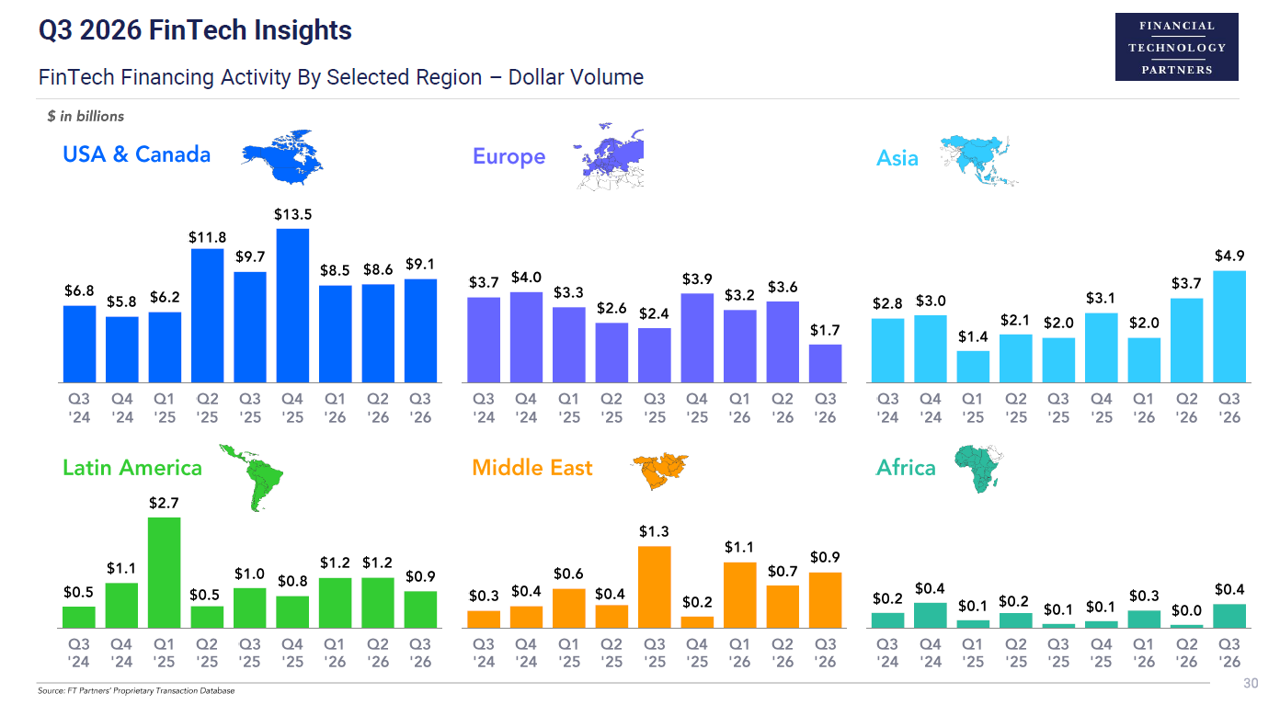
Breakdowns by geography and deal type
FinTech sector and sub-sector highlights
Key Highlights:
Private FinTech financing volume held steady at $18.0 billion in Q3 2026, flat versus Q2 and up 9% year-over-year. Three transactions of $500 million or more contributed $4.1 billion of quarterly volume: Jio Credit's ~$1.9 billion financing, Ant International's $1.2 billion Series A and Polymarket's $1 billion round.
Financing deal count fell to 684, down about 8% sequentially, as capital continued to concentrate in larger rounds. The 124 rounds of $100 million or more in Q1–Q3 2026 already nearly match the full-year 2025 total of 129.
Fifteen new FinTech unicorns were minted in Q3, the most in a single quarter since Q2 2022, led by Angle Health ($2.7 billion) and Moove ($2.1 billion). Several market leaders also reached new valuation highs, including Kraken and Polymarket at $21 billion each, Crypto.com at $20 billion and Revolut at $115 billion through a secondary share sale.
Strategic and corporate venture investors participated in roughly 38% of FinTech rounds in Q1–Q3 2026, including 58% of Crypto & Blockchain rounds. Coinbase Ventures (42 investments) and Tether (17) led strategic activity. Andreessen Horowitz (46), General Catalyst (31) and Lightspeed (26) topped the traditional VC rankings by total FinTech investments.
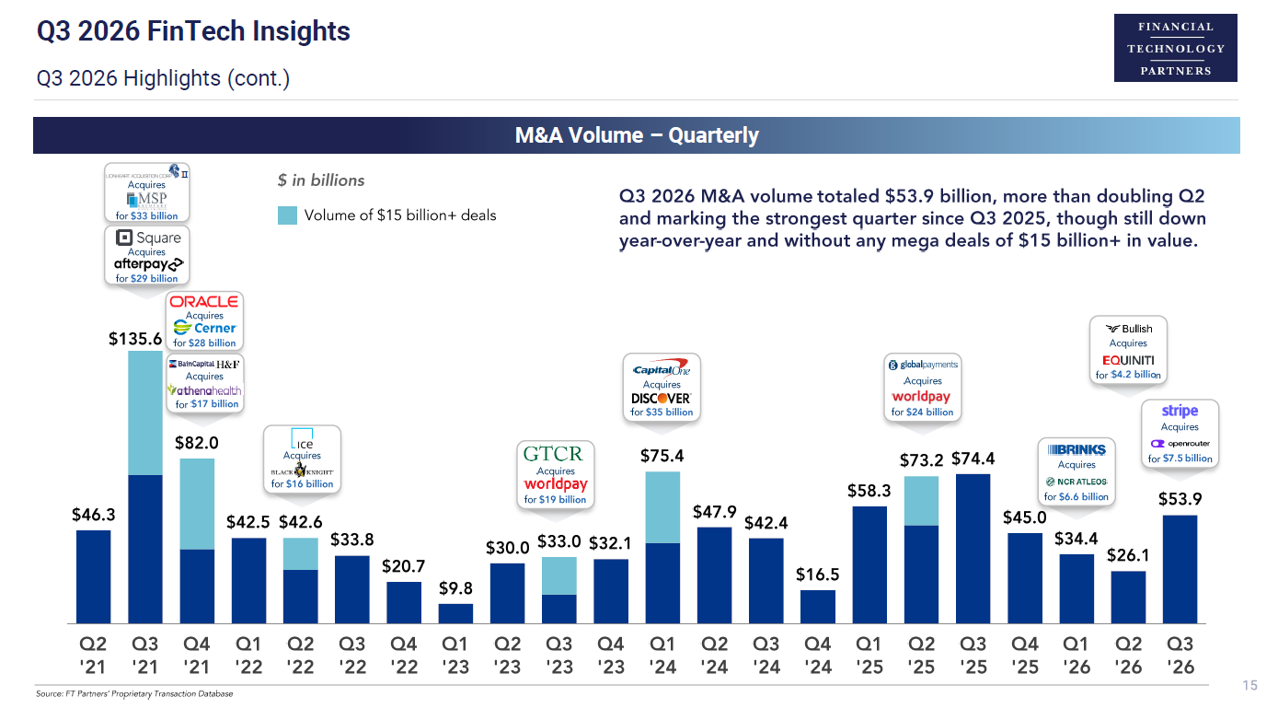
Q3 2026 FinTech M&A volume more than doubled sequentially to $53.9 billion. Thirteen $1 billion+ transactions accounted for $46.2 billion, or 86% of quarterly volume, although no single deal reached $15 billion. Sequence Holdings and Dell Family Office's majority investment in The Baldwin Group, valuing the company at approximately $7.7 billion, led the quarter, alongside Stripe's reported $7.5 billion acquisition of OpenRouter, which highlights the continuing convergence of payments and AI infrastructure.
In Q3 2026, the Banking / Lending Tech sector led financing volume at $4.5 billion, while Financial Management Solutions led deal count with 142 financing rounds.
View More Reports